The Water Deal That Just Rewrote the MUD Tax Math in Fulshear
A buyer comparing two nearly identical four-bedroom homes in Fulshear, both listed in the high $400s, both zoned to Lamar CISD, both with a pool and a three-car garage, will usually ask the agent one question before they ask about square footage: what's the tax rate. It's a fair question, and it's also the wrong question, because the number the agent quotes is a snapshot, not a fact. It changes every year, on purpose, by design, and the direction it moves depends on something almost no one checks before making an offer: how much bond debt is still outstanding on the specific section of the specific district that home sits in.
That distinction just became more relevant. Fulshear's city council recently approved a long-term surface water agreement with the North Fort Bend Water Authority that removes the need for roughly $40 million in planned improvements at the McKinnon Water Plant, freeing up bond capacity the city had been setting aside for that project. It's the kind of council-meeting news that sounds like plumbing and gets treated like plumbing. For anyone comparing communities in Fulshear right now, it's actually a signal about which tax lines are likely to loosen and which aren't.
Every newer master-planned community in Fulshear sits inside a Municipal Utility District, a small local government that borrowed money to build the water lines, sewers, and drainage ponds before a single house existed. The MUD didn't invent that debt. It's repaying it, and it repays it through a property tax levy that shows up as its own line, separate from the county, the school district, and the tiny slice that belongs to the City of Fulshear itself, which set its own ad valorem rate for fiscal year 2025-26 at $0.167903 per $100 of assessed value.
Here's the part that catches people off guard: a MUD tax rate is not fixed. It's a repayment schedule, and repayment schedules behave in a predictable way. Early in a district's life, when the bonds are large and the number of taxable homes is small, the rate is high because the same debt is spread across fewer rooftops. As more homes get built and more of the debt gets paid down, the rate drops. It's the same mechanic as a mortgage amortization table, just applied to a subdivision instead of a single house.
A Public Improvement District works on a completely different clock. A PID assessment is a fixed dollar obligation tied to the original cost of the improvement it funded, not to the home's value. It doesn't rise if the home appreciates and it doesn't fall as the bonds get repaid the way a MUD rate does. PIDs are increasingly common across newer Houston-area master-planned communities, and Texas law treats them seriously enough that a seller has to hand a buyer a specific written disclosure before the contract becomes binding, warning that an unpaid assessment can turn into a lien.
This is where the comparison actually gets useful. Cross Creek West, the newer westward extension of Cross Creek Ranch, currently carries a combined tax rate of 3.16 percent, which the community's own tax page describes as typical for an early-phase MUD. Older sections of Cross Creek Ranch, and comparable established communities like Jordan Ranch, run closer to 2.8 percent once every taxing entity is stacked. Same builders in some cases. Same school district. Same general lifestyle. The gap is almost entirely the bond clock.
| Early-phase district (example: Cross Creek West) | Established district (example: older Cross Creek Ranch sections, Jordan Ranch) | |
|---|---|---|
| Combined effective tax rate | Around 3.16% | Closer to 2.8% |
| Why | Recent bond issuance spread across fewer completed homes | Years of home construction and bond paydown behind it |
| Trajectory | Likely to decline as build-out finishes | Already closer to its floor |
| HOA dues | Roughly $90 to $130 per month is typical across Fulshear's established master-planned communities | Similar range, sometimes with a smaller separate street-light assessment |
None of this means the newer section is a worse buy. New construction usually means fewer near-term repair costs and a longer runway before major systems need replacing. It does mean that comparing two homes purely on list price, without asking where each one sits on its district's repayment curve, is comparing two different financial products that happen to look the same on a flyer.
This is where the recent council decision matters beyond the plumbing. Fulshear's water infrastructure has been financed through a mix of city bonds and the North Fort Bend Water Authority's regional surface water buildout, a project designed to shift the area off groundwater and reduce the land subsidence that comes with heavy aquifer pumping. The city had planned roughly $40 million in improvements at the McKinnon plant to manage that transition. The new agreement makes that spending unnecessary, at least for now, and redirects the bond capacity that would have covered it.
For a homeowner or buyer, freed-up capacity at the city level doesn't erase a MUD's own bond obligations, those are separate governments with separate boards and separate debt. What it does is remove one source of upward pressure on the infrastructure costs that eventually get passed through to residents, whether through city rates, utility fees, or future bond elections tied to water capacity. It's a data point in the same direction the mechanism already points: districts further along in their build-out, with less looming infrastructure need, are the ones more likely to see rate relief rather than a new bond ask.
If you're weighing Cross Creek West against an older section of Cross Creek Ranch, or Fulshear Lakes against Jordan Ranch, the list price and even the quoted tax rate only tell you where things stand today. The question worth asking a builder's sales rep or a seller's agent is a different one: how many bonds does this district still have outstanding, and what does the district's own website or the Fort Bend County Appraisal District show for the trend over the last three years. Most MUDs post their tax rate history publicly, and the pattern is usually visible within a few minutes of looking.
It's also worth confirming whether a specific lot carries a PID on top of its MUD tax, since that assessment behaves nothing like the MUD line and won't move with the bond paydown you might be counting on. The title company will confirm this before closing, but knowing it before you write an offer gives you real negotiating information instead of a surprise.
None of this is a reason to avoid a particular section of Fulshear. It's a reason to ask the second question after you hear the first number.
Does a MUD tax rate ever disappear completely? It can decline substantially once bonds are fully repaid, though it rarely hits zero while the district still funds ongoing operations like drainage maintenance. Some districts eventually get annexed by the city, which changes the tax structure again.
Is a PID worse than a MUD? They fund different things and behave differently, not one universally better. A MUD tax declines over time. A PID assessment stays fixed until the underlying bonds mature, which can run several decades. Neither is inherently a red flag, but they should be budgeted separately and understood on their own terms.
Where do I check a specific address before making an offer? The Fort Bend County Appraisal District's property search shows every taxing entity attached to a parcel, including MUD and PID line items. Most individual districts also publish their own rate history and board minutes online.
Comparing Fulshear communities on price alone tells you what you'll pay at closing. Comparing them on where each district sits in its bond cycle tells you what you'll actually pay five years from now. If you're weighing a specific section against another and want help pulling the tax history and reading it in context, SKW Realty can walk through the numbers with you before you write an offer, not after.
Stay up to date on the latest real estate trends.

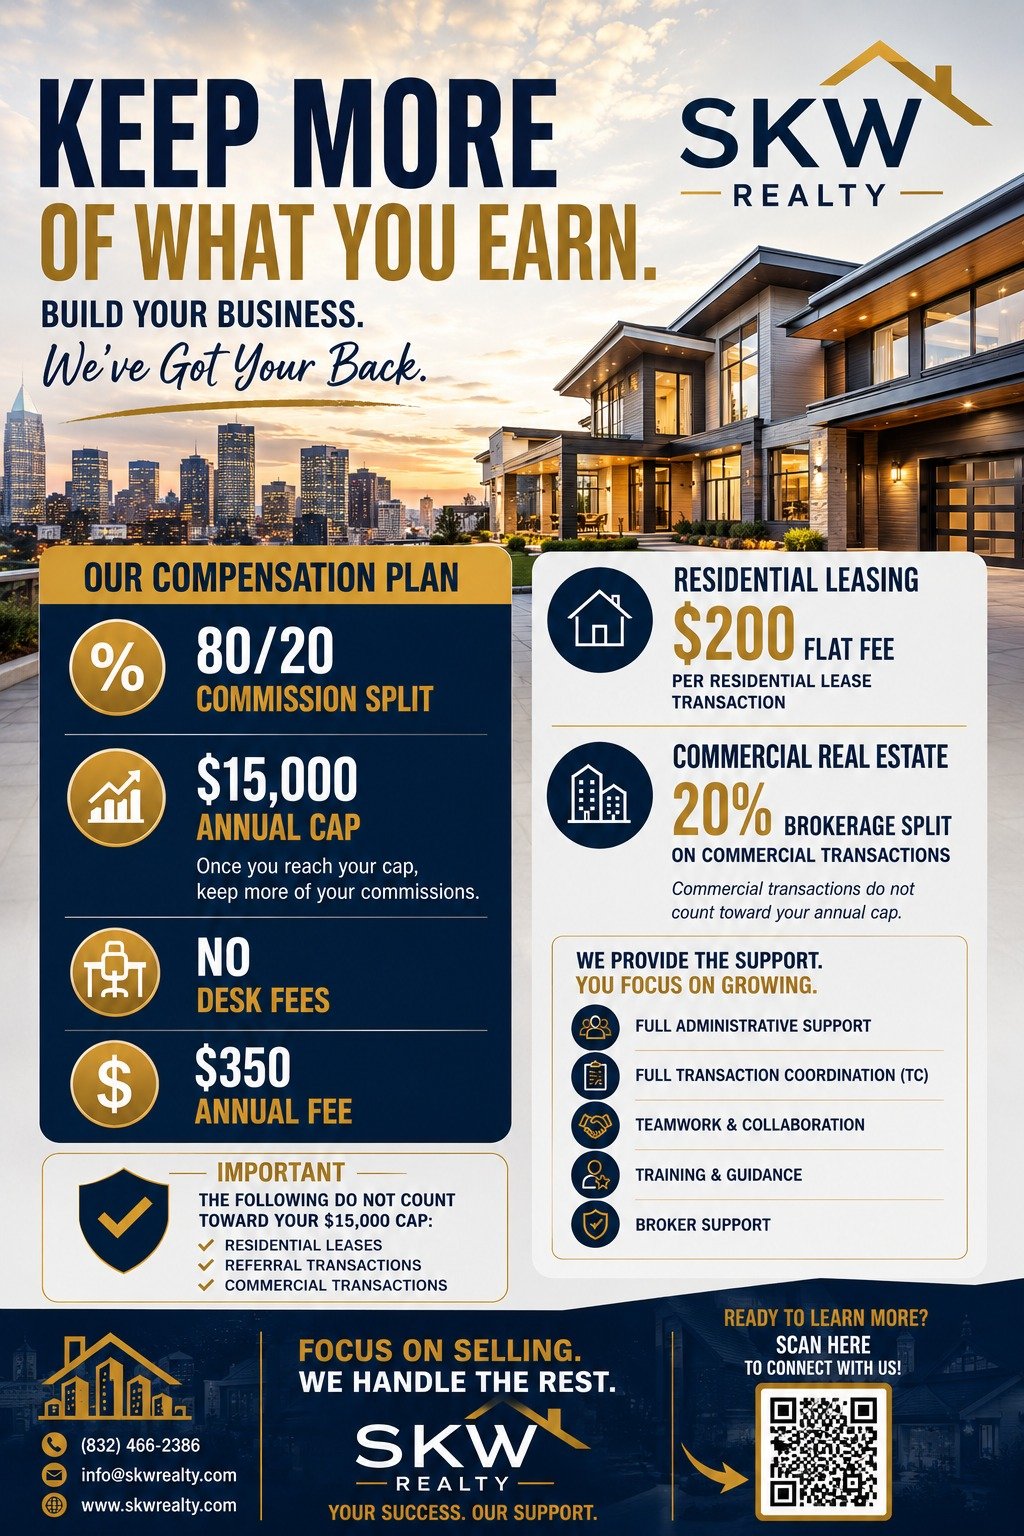
Compensation Plan
Why Agents Are Joining SKW Realty?
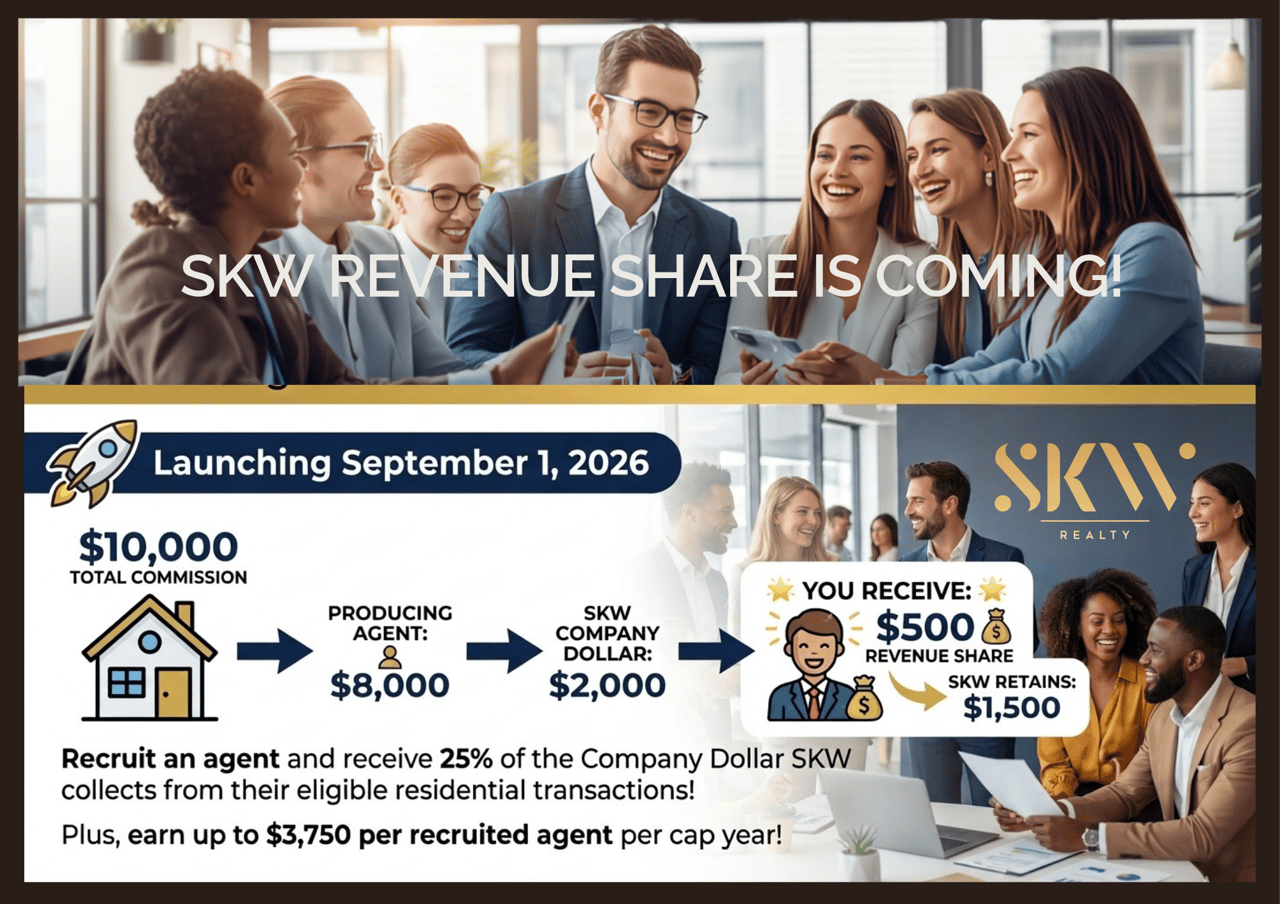
Revenue Share Program
SKW REVENUE SHARE IS COMING!